

Chase Ink No Fee Lifetime Rule
You may be ineligible for the signup bonus on a no-annual-fee Chase Ink card if you currently have, or previously had, any no-annual-fee Chase business card.
Deep Dive into the Chase Ink No Fee Lifetime Rule Rule
The Chase Ink Business Cash and Chase Ink Business Unlimited have long been favorites of points and miles hobbyists. They offer solid signup bonuses, no annual fees, and are business cards that do not count against your 5/24 status.
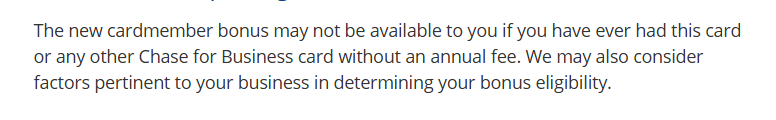
Until late 2025, you could apply for these cards repeatedly and earn another signup bonus when approved. Chase has since added lifetime-style language that makes both cards much more restrictive.
Here is the current language:
What does this mean?
- If you currently have or previously had either the Ink Business Cash or Ink Business Unlimited, you may not be eligible for the signup bonus on either no-annual-fee Ink card.
- In practice, you should generally expect to earn only one signup bonus across the Ink Business Cash and Ink Business Unlimited.
- The restriction is based on whether you have had the card, not simply whether you earned its signup bonus.
- These are Chase's only two no-annual-fee business cards that are not co-branded with an airline or hotel.
This makes choosing between the Ink Business Cash and Ink Business Unlimited much more important than it used to be. Your first card in this group could also be your only opportunity to earn a signup bonus across the two.
Chase Popup
Chase checks your bonus eligibility during the application process and may display a popup if you are not eligible. The popup appears before Chase performs a hard credit check, allowing you to cancel the application rather than continue without the signup bonus.
Chase has generally enforced this restriction consistently, so you should assume that having either no-annual-fee Ink card can make you ineligible for the bonus on both.
One possible exception involves applying under a different business structure. There have been data points of cardholders who originally opened one of these cards as a sole proprietor using their Social Security number later becoming eligible when applying with an EIN. Results have been mixed, however, and Chase still ties business applications to the individual applicant, so this is not something we would count on.
The popup does make it possible to test your eligibility without risking a hard inquiry.
Here is what the popup language looks like:
A quick update about your application. It looks like you’re not eligible for a bonus for a Chase Ink Business Cash credit card. This can happen if you currently have this card or have had it previously. Customers who are applying for a Chase Business card without an annual fee or who have held this card are also ineligible.
Related Rules
How Does This Affect Your Credit Card Strategy?
For anyone who has been in the hobby for a while, this rule is a major change to Chase strategy. Chase has long been one of the easiest ecosystems for building a large transferable points balance, and repeatedly earning signup bonuses on Ink cards was a big part of that.
That is no longer the case. This rule, along with the Chase Ink Lifetime Rule and the new lifetime-style restrictions on Chase Sapphire cards, means there are far fewer opportunities to earn large Ultimate Rewards signup bonuses than there were even in late 2025.
This does not mean Chase Ultimate Rewards are no longer worth pursuing. They remain one of the most useful transferable points currencies. It simply means the strategy has changed. You need to be more selective with signup bonus opportunities, more thoughtful about which cards you open, and more willing to supplement Chase points with co-branded cards and other transferable currencies.
If you've never opened a no-fee Ink card
- Assume you may only have one signup bonus opportunity across the Ink Business Cash and Ink Business Unlimited.
- Choose between the two based on which earning categories and spending multipliers fit your business spending best.
- Because you may only get one bonus across the two cards, waiting for an elevated offer makes the most sense. We suggest keeping enough flexibility in your strategy to jump on a strong offer when it appears.
- Do not open one simply because it has no annual fee. Your first no-fee Ink card could eliminate your opportunity to earn the bonus on the other one later.
The Ink Business Preferred should also be part of your Chase strategy. It has its own lifetime-style restriction, so we recommend being selective there as well and taking advantage of a strong offer when possible.
The Ink Business Premier is separate, but we generally do not recommend it for travelers focused on Ultimate Rewards because its rewards cannot be transferred to airline or hotel partners or combined with transferable Ultimate Rewards points.
Build around Chase transfer partners
With fewer opportunities to earn Ultimate Rewards signup bonuses, it can make more sense to build balances directly with the airline and hotel programs you use most.
- If you frequently transfer to Hyatt, consider the World of Hyatt and World of Hyatt Business cards, then use Ultimate Rewards points for top ups when needed.
- If you frequently transfer to United or Southwest, both programs offer several co-branded cards that can help you build points without using Ultimate Rewards.
- Chase also issues co-branded cards with IHG, Marriott, Air Canada, and British Airways.
- The same strategy applies to Chase transfer partners with co-branded cards issued by other banks, including Wyndham, Flying Blue, JetBlue, and Virgin Atlantic.
If you've opened no-fee Ink cards before
You may no longer be eligible for a signup bonus on either the Ink Business Cash or Ink Business Unlimited. However, Chase's popup allows you to test your eligibility without risking a hard pull.
If you want to try applying, you should generally expect the rule to be enforced. There have been some mixed data points involving applicants who previously opened a card as a sole proprietor and later applied using an EIN, but we would not build a strategy around that exception. It may allow some applicants to earn more than one bonus, but the days of repeatedly opening Ink cards for signup bonuses are over.
If Chase does not offer you another no-fee Ink bonus, shift your focus elsewhere. That could mean the Ink Business Preferred, Chase co-branded cards, or other transferable points ecosystems such as American Express Membership Rewards, Bilt Rewards, Citi ThankYou Points, or Capital One Miles.
The biggest change is that Chase can no longer be treated as an endless source of signup bonuses. Ultimate Rewards are still extremely useful, but building a large balance now requires a more diversified, long-term strategy. With lifetime-style restrictions now covering the major cards that earn transferable Ultimate Rewards, the number of signup bonuses you can earn is much more limited than it used to be.
Importance of this Rule
* * *
The importance of this rule depends largely on how long you've been in the points and miles hobby. If you're just getting started, it simply becomes another rule to build your strategy around. Since you likely weren't relying on repeat Ink welcome offers, your long-term approach doesn't change much. Just be selective about which no-annual-fee Ink card you choose and wait for an elevated offer when possible.
For experienced hobbyists, however, this is one of the biggest changes Chase has made in years. If you regularly earned repeat Ink welcome offers or played two-player mode with a spouse or partner, this rule removes what was once one of the best ways to generate large balances of Ultimate Rewards points. There are still plenty of ways to earn valuable travel rewards, but the strategy has shifted significantly, as Chase Ultimate Rewards can no longer be the main focus of your points collecting.
Cards Subject to This Rule
FAQs
Are there exceptions to this rule?
There may be a few. One potential exception involves applicants who originally opened one of these cards as a sole proprietor using only their Social Security number but now have a business with its own EIN. Some hobbyists have successfully received another welcome offer in this situation, though approval is far from guaranteed. Fortunately, Chase's popup appears before a hard credit inquiry, so there is little downside to testing your eligibility. Just have a backup plan if you are not offered the bonus.
How do I check my status?
If you add all of your credit cards to Points Navigator, we track this rule and the other major credit card eligibility rules that affect you. With dozens of application and welcome offer restrictions across the major issuers, keeping track of your eligibility manually has become increasingly difficult.
Do other business cards count for this rule?
No. This specific rule applies to Chase business cards without an annual fee, which currently means the Ink Business Cash and Ink Business Unlimited. Other Chase business cards, including the Ink Business Preferred and Ink Business Premier, have separate bonus eligibility rules.
Do product changes on existing cards count for this rule?
Yes, they can. Chase's terms say the bonus may not be available if you have ever had the card, so product changing into the Ink Business Cash or Ink Business Unlimited could affect your future bonus eligibility even if you never earned a signup bonus on that card. Because of that, we generally would not product change into one of these cards if you still hope to earn its signup bonus in the future.
About Approval Rules
Collecting credit card points is largely driven by understanding and abiding by bank rules regarding approval (or disapproval) of cards. So here's what you need to know:
- Approval rules are rarely fully publicized by the banks
- We use our own research and data points from other users in creating the rules listing
- Our goal in sharing/using the rule listings is to provide you guidance to avoid getting declined
- There can sometimes be exceptions to the rules, but we try to take a more cautious approach in advising you.